TerraIndex™ HPI Commentary
August 2026
AUGUST 2026 — Price Weakness Broadens, but the Market Has Not Broken
Published September 24, 2026 | Data through August 2026
Monthly declines became nearly universal across major markets even as annual home values remained comparatively stable — a divergence increasingly shaped by affordability constraints and historically thin transaction volume.
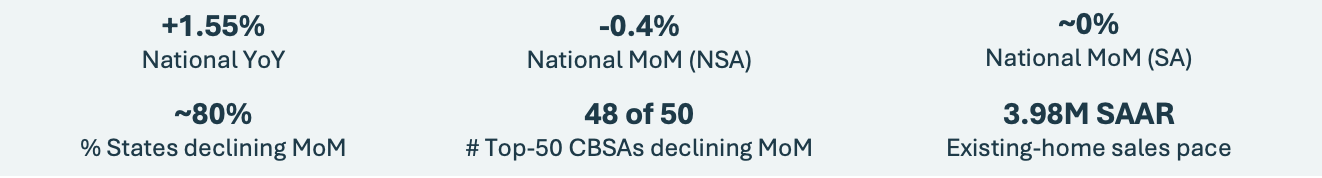
August: broad monthly weakness, stable annual values
TerraIndex shows U.S. home values up 1.5% year over year in August, consistent with the prior three months. But the monthly picture weakened further: non-seasonally adjusted values fell 0.4%, following July’s 0.3% decline, while seasonally adjusted values were essentially unchanged. Nearly 80% of states declined month over month, up from roughly 70% in July, and 48 of the top 50 CBSAs posted monthly depreciation.
The contrast is important. Roughly 40% of the top 50 CBSAs were negative year over year — an improvement from 46% in July — even as monthly declines became almost universal. The data therefore do not describe a national price break. They describe a market in which late-summer weakness has broadened considerably while the underlying annual value level remains comparatively stable.
Affordability is still setting the speed limit
Mortgage rates offered little relief during August. Freddie Mac’s 30-year fixed rate was 6.69% on August 6 and remained tightly clustered between 6.65% and 6.67% through month-end. At those levels, affordability remains restrictive for many households, limiting the demand response even where sellers have become more flexible.
Realtor.com’s August data reinforce the point. Active listings rose 3.6% from a year earlier to about 1.14 million, while new listings were essentially flat year over year. Median list price declined 1.3% year over year, 20.4% of listings had a price reduction, and contract signings weakened. Yet median time on market was 60 days — unchanged from a year earlier. That combination suggests adjustment and negotiation, not a disorderly market.
Transaction scarcity is becoming part of the measurement story
The unusually low level of housing turnover deserves particular attention. NAR reported August existing-home sales at a seasonally adjusted annual rate of 3.98 million, down 2.0% from July and 1.2% from a year earlier. Inventory rose to 1.62 million homes, or 4.9 months of supply, while the median existing-home sales price was still 1.6% above August 2025.
The current sales pace sits near levels last seen in the mid-1990s, despite a materially larger U.S. population and housing stock. In practical terms, only a relatively small portion of the residential market is repricing through arm’s-length transactions. That matters for market interpretation: when turnover is unusually thin, the homes that do transact can become less representative of the broader housing stock, and recent-sale evidence can become sparse in individual local markets.
Quantarium sees the same issue at the model level. In some geographies, the pool of sufficiently recent transactions has become thin enough that recent minimum transaction specifications in the QVM model library cannot always be deployed with the preferred sample depth. This is not presently a material coverage issue, but it illustrates why QVM’s broader valuation signals and model flexibility become more important when local price discovery is based on fewer transactions.
The regional divide remains — but is becoming less clean
The South and West remain the principal sources of year-over-year weakness in TerraIndex, while New York, Milwaukee and Hartford continue to outperform among large markets. August, however, brought clearer evidence that monthly softness is spreading into previously more resilient Midwest and Northeast markets.
Realtor.com reported active inventory up 10.5% year over year in the Midwest and 9.1% in the Northeast, versus 3.2% in the West and 1.1% in the South. Price cuts also ran above year-earlier levels in the Midwest and Northeast. At the same time, those regions continue to contain many of the country’s most competitive markets. The geographic advantage has therefore not disappeared; rather, August suggests that seasonal cooling is no longer confined primarily to the South and West.
Florida illustrates why regional and even metropolitan averages can conceal important submarket differences. HousingWire reported that Florida active single-family inventory remained well above early-2023 levels, with widespread price reductions, while its Orlando analysis found sharply different conditions between vacation-oriented areas, new-construction-heavy suburbs and core neighborhoods. Insurance costs, builder incentives and affordability are increasingly interacting with mortgage rates to determine local outcomes.
The broader economy is slowing housing without forcing a break
The labor market remains supportive enough to limit forced selling. U.S. nonfarm payrolls increased by 162,000 in August and unemployment held at 4.1%. At the same time, inflation remained elevated: CPI rose 0.4% in August and 3.4% over the prior year, while core CPI increased 0.3% for the month and 2.4% year over year. That inflation backdrop helped keep financing costs restrictive through the period.
New construction sent mixed signals. Total housing starts fell 2.6% in August to a 1.275 million annual rate, while single-family starts rose 7.6%. Permits declined 2.7% overall and 1.8% for single-family homes. MBA’s Builder Application Survey showed applications for new-home purchases down 5.5% year over year and 6% from July — the fifth consecutive monthly decline — underscoring the pressure higher rates continue to place on buyer demand.
What to watch next
The key question is whether August represents an unusually broad seasonal reset or the beginning of more persistent price erosion. Early September flow data deserve attention. HousingWire reported that for much of August pending sales absorbed incoming new listings at ratios in the mid-90s, but by the week ending September 18 the ratio had fallen to 86 pending sales for every 100 new listings. Because the reading followed Labor Day, it is better treated as a signal to monitor than a trend to declare.
Three indicators should clarify the direction: whether pending sales keep pace with new listings, whether price reductions continue to spread, and whether days on market begin to separate materially from year-earlier levels. A persistent gap between new supply and contract activity would increase the likelihood that today’s broad monthly weakness carries further into the fall.
Bottom Line
August extends the sequence that began after the spring rebound: affordability reasserted itself in April, the market moved into a holding pattern in May, momentum faded in June, and weakness became broad-based in July. August moved one step further — monthly depreciation spread across nearly the entire major-market landscape.
Yet the annual TerraIndex reading remains stable at +1.5%, and existing-home prices remain positive year over year. The market appears to be adjusting first through lower transaction volume, more inventory, seller price reductions and seasonal monthly declines rather than through wholesale repricing of the broader housing stock. With turnover near multi-decade lows, that distinction is relevant: fewer transactions can slow price discovery even while the value of the overall housing stock remains comparatively resilient.
External Market Indicators Referenced
- Quantarium TerraIndex HPI, reporting through August 2026.
- Freddie Mac, Primary Mortgage Market Survey, August 2026 weekly observations.
- National Association of Realtors, Existing-Home Sales, August 2026 (released September 10, 2026).
- Realtor.com Economic Research, August 2026 Monthly Housing Trends (released September 2, 2026).
- U.S. Bureau of Labor Statistics, Employment Situation — August 2026 (released September 4, 2026).
- U.S. Bureau of Labor Statistics, Consumer Price Index — August 2026 (released September 11, 2026).
- U.S. Census Bureau / HUD, New Residential Construction — August 2026 (released September 17, 2026).
- Mortgage Bankers Association, Builder Application Survey — August 2026 (released September 15, 2026).
- HousingWire Data and Housing Market coverage supplied for review, including September 2026 analyses of listings/pending sales and Florida/Orlando market conditions.
Quantarium Research | TerraIndex Commentary | August 2026.
About Quantarium
For business inquiries, please contact us at 424.210.8847 or discover@quantarium.com.