TerraIndex™ HPI Commentary
September 2026
SEPTEMBER 2026 — Housing Weakness Broadens as Annual Price Growth Begins to Fade
Published October 26, 2026 | Data through September 2026
September’s broadening price weakness is increasingly visible in annual home values. A thin transaction market does not eliminate price pressure — and distinguishing transaction activity from changes across the broader housing stock is central to interpreting this cycle.
Quick Takeaway
September’s TerraIndex results indicate a housing slowdown that is becoming more persistent. Monthly depreciation now spans nearly the entire country, and national annual appreciation has begun to recede. Rising borrowing costs, weaker buyer absorption and widespread price reductions are consistent with a market in which purchasing power and seller expectations remain misaligned.
Still, a national seasonally adjusted decline of 0.1% is modest, and annual appreciation remains positive. The evidence supports broadening weakness, not a definitive nationwide housing correction. The question for the fourth quarter is whether limited transaction activity continues to translate into lower values across the housing stock, or whether constrained supply and owners’ ability to defer sales temper the adjustment.
September: the slowdown reaches annual appreciation
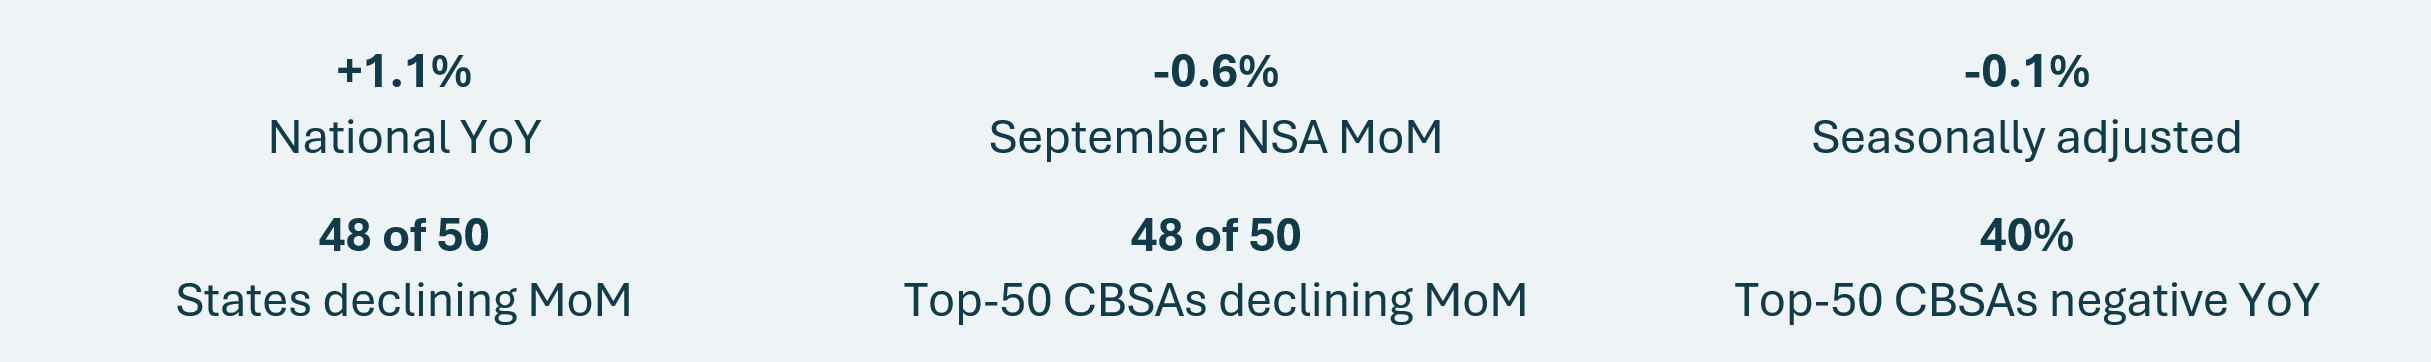
U.S. home values declined 0.6% month over month on a non-seasonally adjusted (NSA) basis in September, following declines of 0.3% in July and 0.4% in August. On a seasonally adjusted basis, national values declined a more modest 0.1%. Normal autumn seasonality remains an important part of the picture, but does not fully account for the loss of momentum.
More significantly, annual appreciation slowed to 1.1%, from roughly 1.5% over the preceding four months. Monthly weakness, previously accompanied by comparatively stable annual appreciation, is now beginning to affect the longer-term measure. The pattern is consistent with a spring recovery that failed to develop into sustained price momentum.
The distinction between transactions and home values is increasingly consequential. A shortage of transactions does not necessarily produce a shortage of price pressure. Listings, pending contracts and seller concessions reveal changing market behavior; TerraIndex complements those signals by measuring value changes across the broader residential housing stock, not only the subset of homes that sell.
Mortgage rates and affordability constrain demand
Mortgage rates reversed their earlier decline during September, increasing from approximately 6.7% early in the month to around 7% late in September, according to Freddie Mac’s Primary Mortgage Market Survey. Higher financing costs narrowed purchasing power and complicated the negotiation between sellers anchored to prior valuations and buyers constrained by monthly payments.
Realtor.com’s September housing report described higher active inventory, weaker pending activity and elevated price reductions. Together, these signals suggest that demand is adjusting more quickly than many sellers’ asking prices. The consequence can be prolonged low turnover before broader valuation measures register material declines.
Inventory and the pace of buyer absorption
HousingWire reported approximately 86 pending sales for every 100 new single-family listings in the week ending September 18, compared with 97 in the corresponding week of 2025. The post–Labor Day timing warrants caution, but the gap was consistent with a broader late-summer pattern of demand absorbing less incoming supply.
Inventory itself is not a sufficient measure of market strength. An increase can reflect homes remaining unsold rather than a surge of willing sellers; a decline can reflect withdrawn listings rather than renewed buyer demand. National delisting evidence does not yet establish a widespread withdrawal wave. For now, slower absorption and greater pricing negotiation are better-supported interpretations than broad seller capitulation.
Regional weakness broadens beyond familiar markets
TerraIndex recorded annual depreciation in ten states, led by Washington, Colorado and Georgia. Wisconsin, Mississippi and New York continued to post gains near 5%. Yet on a monthly NSA basis, every state except Mississippi and West Virginia declined; Vermont and Maine were among the larger monthly decliners. Previously resilient regions are not immune to the current loss of momentum.
Among the 50 largest CBSAs, 40% were negative year over year. Austin remained the weakest annual performer, with Seattle closing the gap, while Milwaukee, New York and Hartford outperformed. On a monthly basis, 48 of the 50 markets declined, with Miami and Phoenix the only modest gainers. San Jose, Denver, Philadelphia, Seattle and Dallas each fell by more than 1.2% NSA. The median monthly change across the top 50 remained at -0.6%.
Low turnover complicates price discovery
Existing-home sales rose 1.5% month over month in the September report discussed by HousingWire in October, but were still 2.2% below a year earlier. Completed sales generally reflect contracts signed earlier and may not capture the full impact of September’s renewed mortgage-rate increase. Meanwhile, August new-home sales reached a seasonally adjusted annual pace of 684,000, aided in part by builders’ ability to offer financing incentives unavailable to many existing homeowners.
The combination reinforces a structural distinction: builders can sometimes protect transaction volume through rate buydowns, while resale owners may instead wait, negotiate or defer selling. With turnover historically constrained, a relatively small set of transactions can become less representative of the full stock of homes. Whole-stock valuation signals, such as TerraIndex, therefore provide an important complement to transaction-based market indicators, while still requiring careful interpretation of model uncertainty and local conditions.
External Market Indicators Referenced
- Quantarium, TerraIndex HPI Report — September 2026 (released October 14, 2026).
- Freddie Mac, Primary Mortgage Market Survey, September 2026.
- Realtor.com Research, September 2026 Monthly Housing Trends Report (published September 30, 2026).
- HousingWire / HW Data, “Why New Listings and Pending Sales Matter Before Inventory Moves” (September 22, 2026).
- HousingWire, “New Home Sales Are at an 8-Month High but Still Stuck After 10 Years” (September 24, 2026).
- HousingWire, “Existing Home Sales Beat Estimates, but Don’t Reflect Recent Higher Rates” (October 13, 2026; retrospective September activity).
- HousingWire / HW Data, “Why Falling Housing Inventory Is Sending Sellers the Wrong Signal” (October 14, 2026; subsequent market context).
Quantarium Research | TerraIndex Commentary | September 2026.
About Quantarium
For business inquiries, please contact us at 424.210.8847 or discover@quantarium.com.